
For most Australians: Revolut is cheaper if you convert under A$2,000 a month, Wise is better for larger or one-off conversions, and neither should be used on a weekend. Revolut’s Standard plan is free up to A$2,000 per rolling month and then charges 0.5%. Wise charges a visible fee from the first dollar, typically well under 1%, which falls as the amount rises.
Last checked 21 September 2026. We have no commercial relationship with either provider. If that changes, it will be disclosed here.
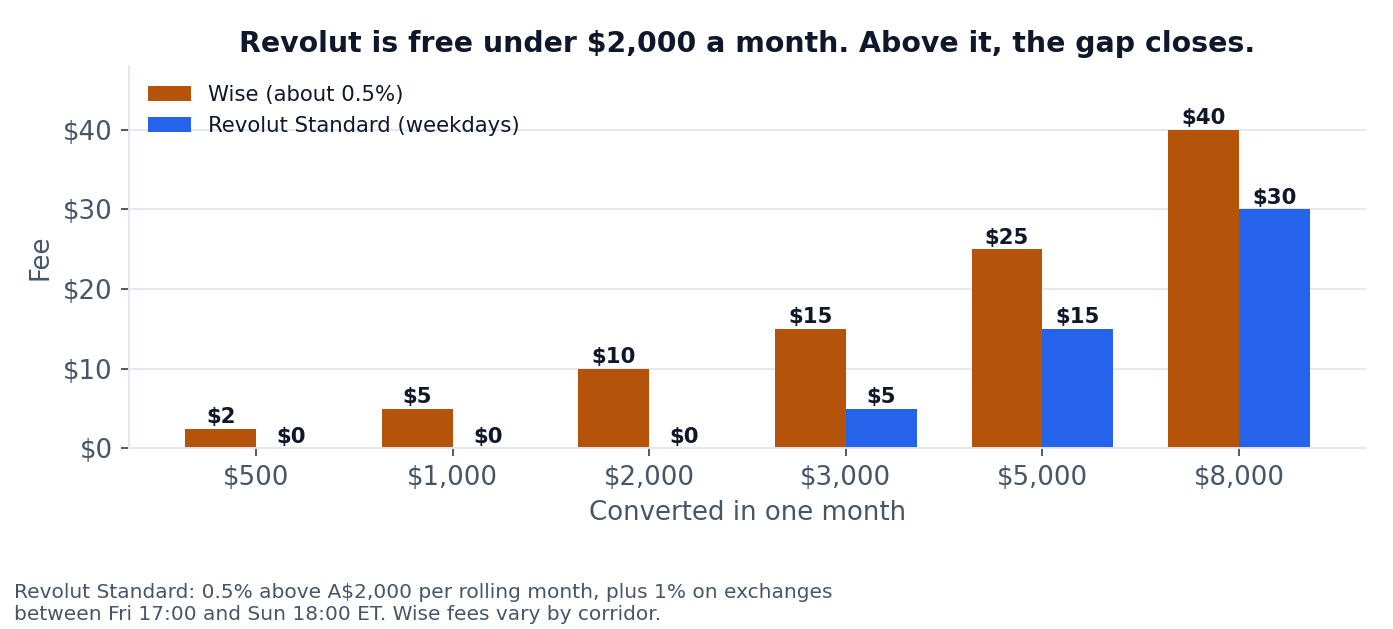
They charge in opposite shapes
Both use the real mid-market exchange rate, so neither is hiding a margin inside the rate the way a bank or an airport kiosk does. The difference is the fee structure sitting on top.
| Wise | Revolut (Standard) | |
|---|---|---|
| Exchange rate | Mid-market | Mid-market |
| Conversion fee | Visible fee from the first dollar, usually well under 1%, falling on larger amounts | Free to A$2,000 per rolling month, then 0.5% |
| Weekend surcharge | None | +1% between Fri 17:00 and Sun 18:00 ET |
| ATM allowance | Monthly free allowance, then fees | A$350 or 5 withdrawals per rolling month |
| ATM fee after that | Per-withdrawal plus a percentage | 2% or A$1.50, whichever is greater |
| Card cost | $10 physical, digital free | Free on Standard |
| Best at | Larger conversions, transparency | Small regular spend inside the allowance |
Where the crossover sits
Under A$2,000 a month, Revolut wins outright, because its fee is zero and Wise’s is not. Above it, Revolut charges 0.5% on the excess while Wise charges its rate on the whole amount, so the gap narrows but Revolut usually stays ahead on a straight weekday conversion.
That comparison flips the moment timing enters it. A A$3,000 conversion on a Saturday costs a Revolut Standard customer the 0.5% on the excess plus 1% on the lot. The same conversion on Tuesday costs a fraction of that. Wise has no equivalent penalty.
So the honest rule is not “Revolut is cheaper”. It is “Revolut is cheaper if you stay inside the allowance and convert on a weekday”, and Wise is the one that behaves the same every day of the week.
The weekend markup, in plain terms
Currency markets close over the weekend. Providers offering mid-market rates when there is no live market are quoting into a gap, and they price that risk. Revolut passes it on as an explicit 1% for Standard customers between Friday 17:00 and Sunday 18:00 US Eastern time.
For Australians that window lands awkwardly. Friday 17:00 ET is early Saturday morning in Australia, and Sunday 18:00 ET is Monday morning here. In practice, the whole Australian weekend sits inside the surcharge. If you top up a travel balance on a Sunday afternoon before flying out Monday, you are paying for it.
Convert on a weekday and the problem disappears.
Which to use
Revolut suits you if your overseas spending is modest and regular, you stay under A$2,000 in a month, and you can convert during the week.
Wise suits you if you are converting a larger sum at once, sending money rather than spending it, holding several currencies, or you simply want a fee you can see and predict without checking the clock.
There is no rule against both. They are free to hold, and using Revolut inside its allowance while running larger conversions through Wise is a reasonable setup that costs nothing to maintain.
Worth noting that for pure card spending overseas, a no foreign transaction fee debit card can beat both, because it charges nothing on the transaction at all.
Common questions
Do either of them mark up the exchange rate?
No. Both use the mid-market rate and charge a separate fee. That is what separates them from banks and airport exchange, where the margin is inside the rate and much harder to see.
Is Revolut’s paid plan worth it?
It depends entirely on how much you convert. The paid tiers raise or remove the fee-free allowance, so the subscription only pays if the fees you avoid exceed it. Work out your monthly conversion first, then check whether the maths clears the fee.
Which is better for sending money to family overseas?
Wise, generally. That is the product it was built for, its fee falls on larger amounts, and there is no weekend penalty on a transfer you may not be able to time.
Can I use either as my main account?
People do, but they are payment and currency products rather than a replacement for an Australian bank account, and the protections are not identical. Read the product disclosure before moving your salary.
Do the fees change?
Frequently. Wise’s conversion fee varies by currency pair and amount, and Revolut has restructured its allowances before. Both publish current fees in-app, which is the only figure worth trusting at the moment you convert.